Hi team,
What a week! The S&P 500 finished 2.5% higher for the week, even after falling 0.4% on Friday. We saw some strong bounces, but with inflation still in focus and major resistance overhead, I’m not treating every rally as an all-clear.
October CPI rose 0.4% month over month, with core CPI up 0.3%. Producer prices rose 0.3%. As always, the headline matters, but so does the market’s reaction to it.
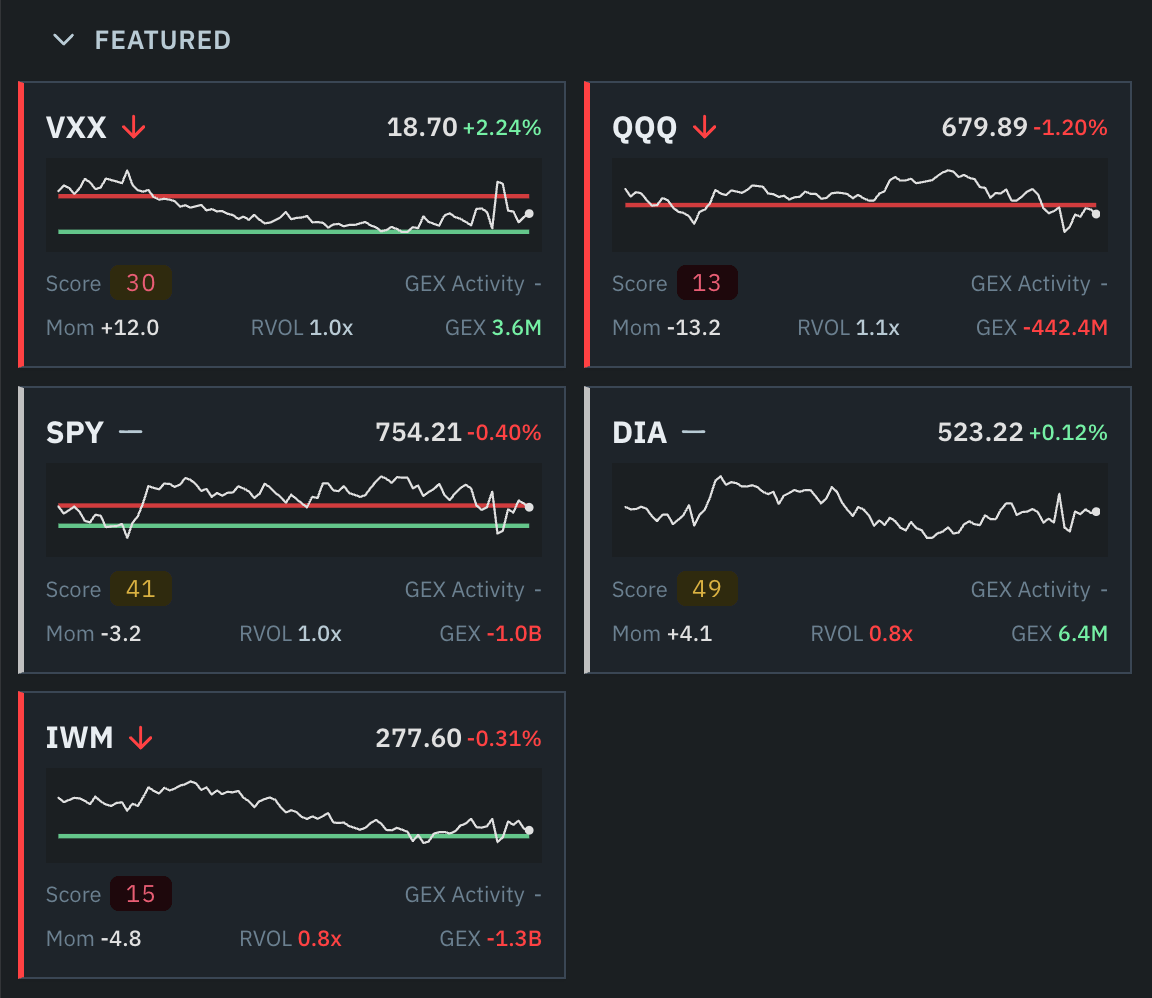
For me, trend remains the first filter. TMAD’s latest reading shows SPY in a sideways trend and QQQ still in a downtrend. A sharp bounce can be a great trade, but it doesn’t automatically mean the downtrend is over. Be careful chasing a move simply because you feel you missed it.
SPX Levels
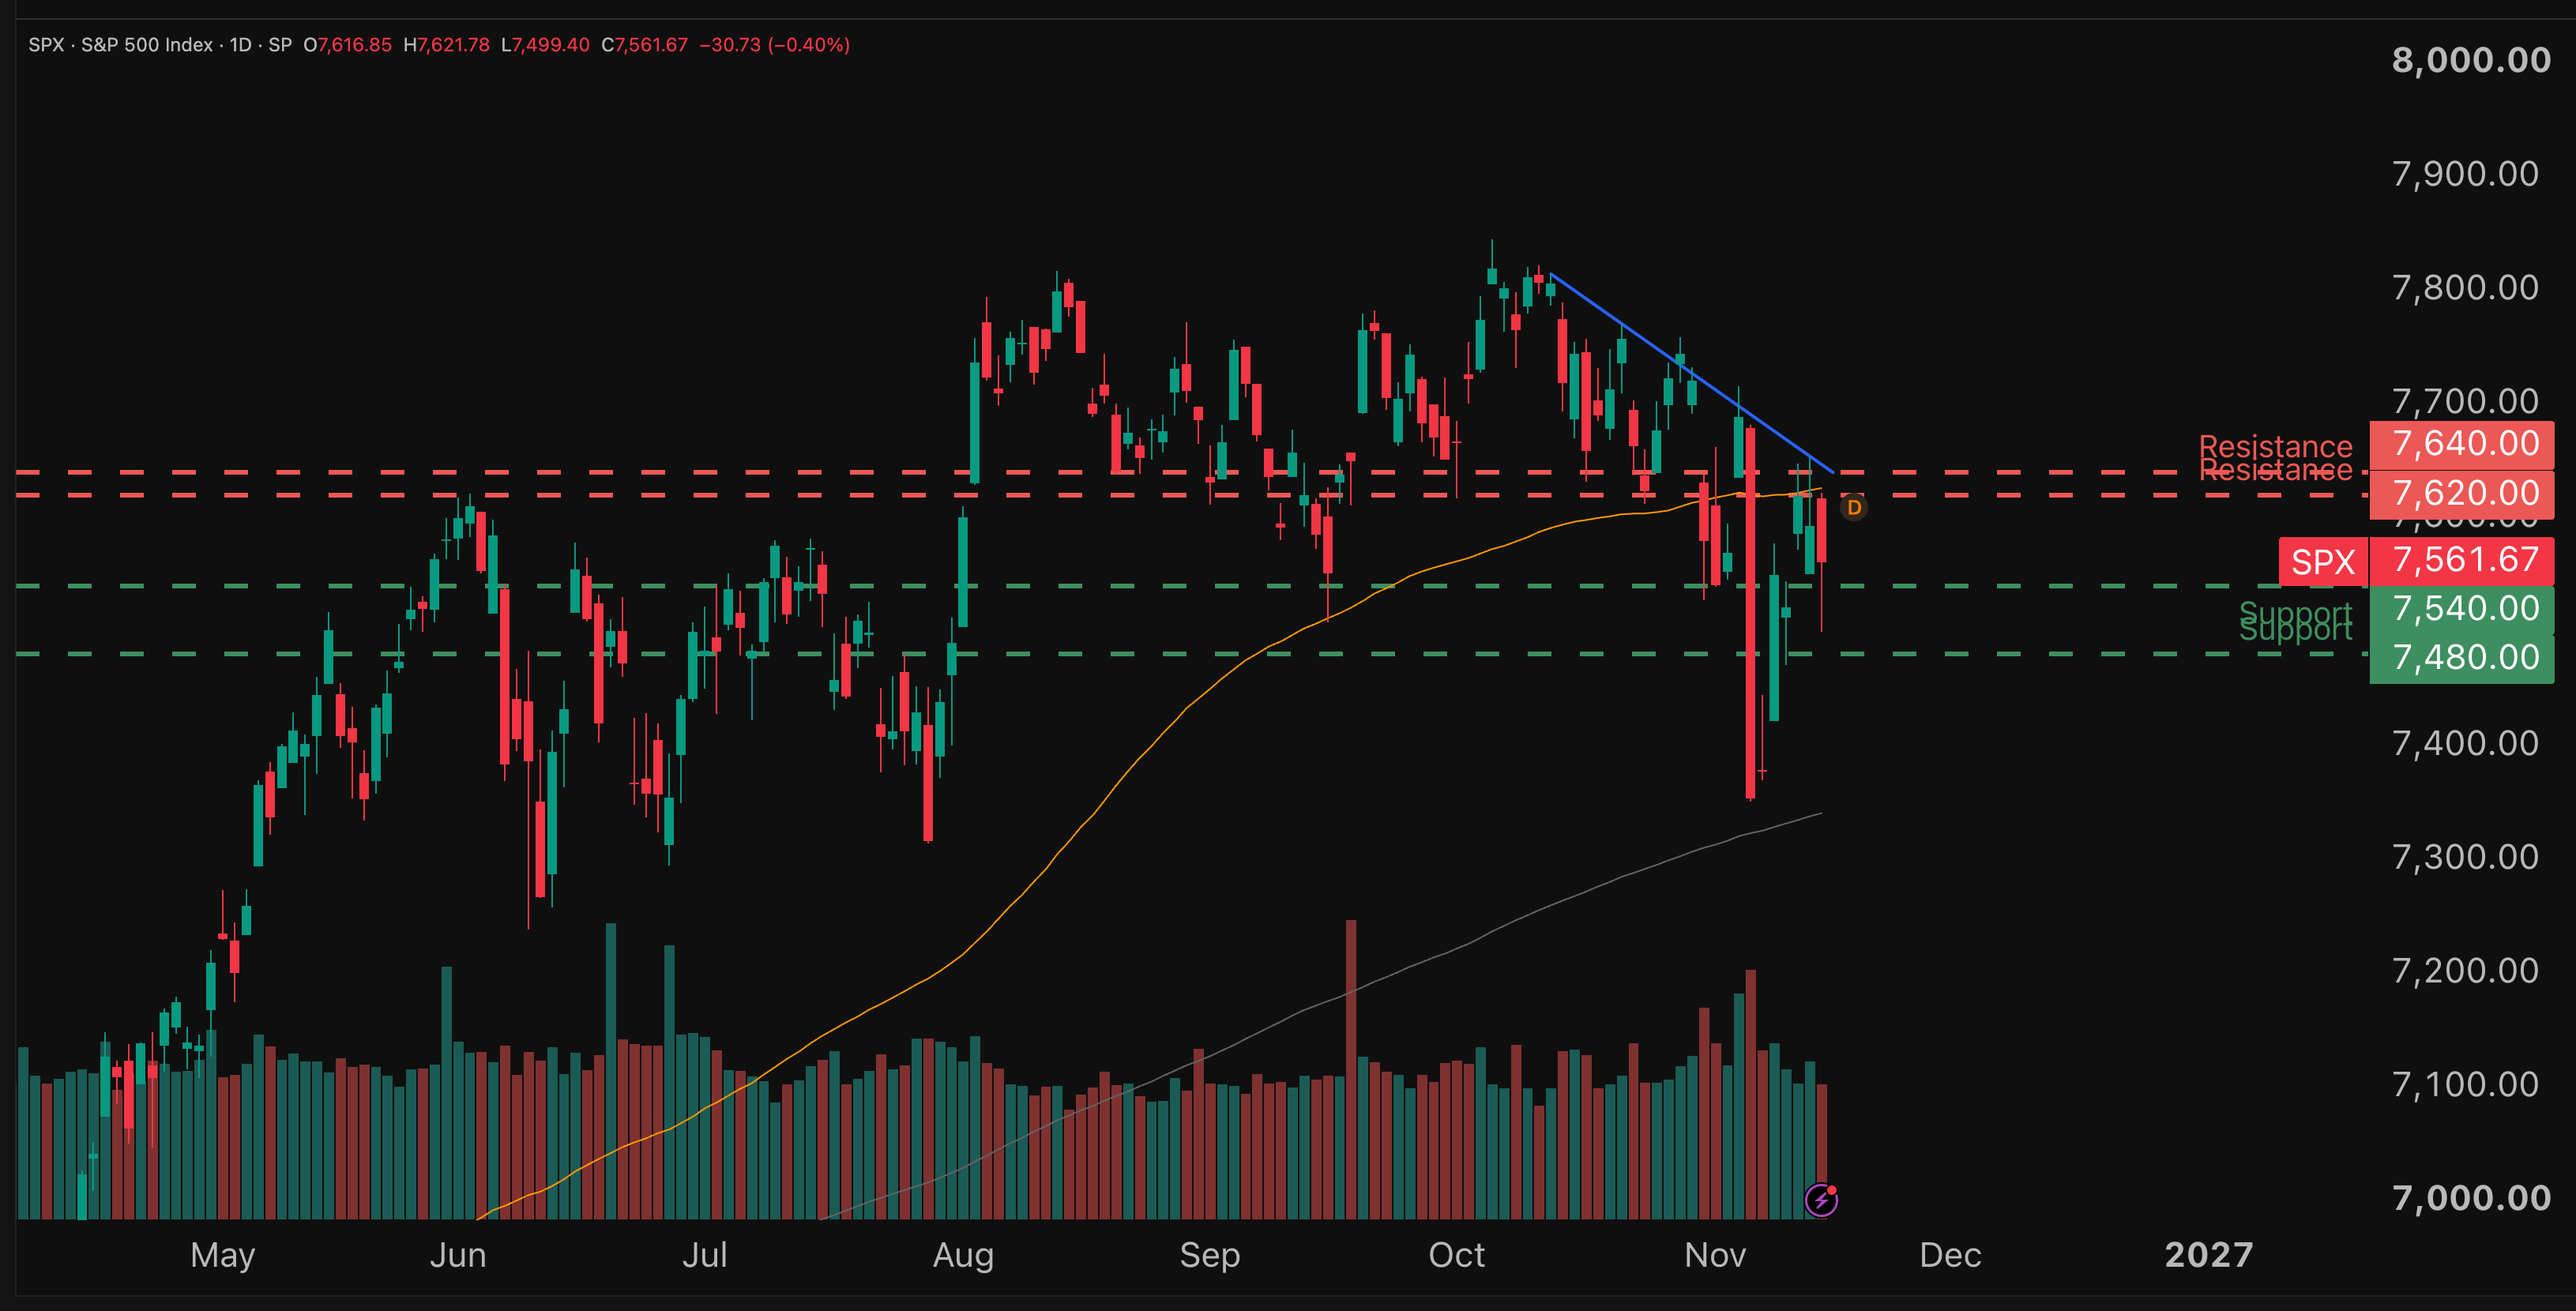
Resistance: 7,620 / 7,640
Support: 7,540 / 7,480
We are below a trendline and below 100DMA. Guilty until proven innocent.
Stocks aren’t the only charts we’re watching. Alessio has also been tracking the dollar and bond yields, and both moved higher last week. The 10-year Treasury yield climbed from 4.86% to 5.15%, while the dollar strengthened. Higher yields can pressure growth-stock valuations and raise financing costs, while a stronger dollar can weigh on U.S. companies’ overseas earnings. This doesn’t guarantee another selloff, but it’s another reason to stay selective and avoid assuming every bounce marks a new uptrend.